Low-interest loans kept many eateries afloat. But the industry never recovered enough for them to repay the debt
For almost 20 years, Jai Mazumdar has served vegetarian curries, samosas, gulab jamun and other Indian delicacies at Spice N Curry, a cafe and grocery nestled inside a modest strip mall near Florida International University (FIU) in Miami. When the Covid-19 pandemic devastated his business, as it did with so many restaurants, Mazumdar took out a $370,000 economic injury disaster loan (EIDL) from the federal government in early 2021.
At the time, it provided a desperately needed lifeline. He was confident that once business returned to normal he could begin repaying the 30-year loan, which came with a low 3.75% interest rate and a 30-month deferment period. But when his business didn’t recover, the disaster loan turned out to be a disaster of its own.
The Spice N Curry cafe relied heavily on traffic from FIU. Since many students and faculty were studying and working remotely both during and after the pandemic, Mazumdar’s lunch business took a major hit. As the losses mounted, he applied for additional EIDL funds and was extended another $87,000 loan the following year.
Borrowers with EIDLs totaling more than $200,000 were required to personally guarantee the loan, which meant that if they default, the government would be able to seize their personal assets. Five years later, Mazumdar is struggling to make his monthly payments, and he’s losing faith that he’ll ever be able to fully repay the loans.
Since Congress passed the Coronavirus Aid, Relief, and Economic Security (Cares) Act in March 2020, the federal government has issued 3.9m Covid-related EIDLs totaling $378.4bn to businesses that faced hardship as a result of the pandemic. The Small Business Administration (SBA) was tasked with administering the loans – up to $2m per individual applicant. Despite the attractive rates and flexible terms, according to a congressional report released earlier this year, EIDL defaults have steadily risen to over 30%, resulting in $75.2bn in charged-off loans as of last June.
“Covid was an extinction event for tens of thousands of restaurants,” said Erika Polmar, executive director of the Independent Restaurant Coalition, a non-profit advocacy group for independent bars and restaurants in the US. “The ones that survived, if they didn’t receive [restaurant revitalization fund] grants, had to pay off all that debt from small businesses loans or EIDLs. Local initiatives that promised rent relief or eviction moratoriums often fell through. So they moved through 2022 and beyond trying to pay off their debt and weren’t able to reinvest in their businesses.”
Mazumdar says his business is worse off today than it was during Covid – a sentiment echoed by other operators whose businesses have been negatively affected by rising food, labor and energy costs. “There is a tsunami going on right now,” he said. “Rents are very high. The average population doesn’t have spending power. There is a lack of qualified labor. Tourism has also declined here. Everyone is just nervous about when the next leg of the stool is going to collapse.”
Five years after he took the loans, Mazumdar says the EIDL money is gone. Initially, he used the funds to refurbish the space and upgrade equipment, installing new refrigeration and freezer units to increase his retail inventory. He used the rest to cover operating expenses. After finally reopening the cafe in 2022, sales declined so badly that he decided to close the dining room permanently after just a year and a half.
“My monthly EIDL payment is $1,900, and my home mortgage is $1,600,” he said. “I had to rent out a room in my own home so I could have extra income to cover part of the payment.” His business has lost money every year since Covid, yet he’s managed to stay current with his loan payments. “I’ve been working seven days a week, 12 hours a day for the last three years. It’s become a completely hand-to-mouth existence.”
When borrowers exceed 120 days past due on their EIDL payments, the loans are transferred to the US treasury department for collection. That results in additional fees and penalties that typically amount to about 30% of the principal. When the loans are personally guaranteed, the IRS can garnish the delinquent borrower’s wages, tax refunds or a percentage of their social security benefits.
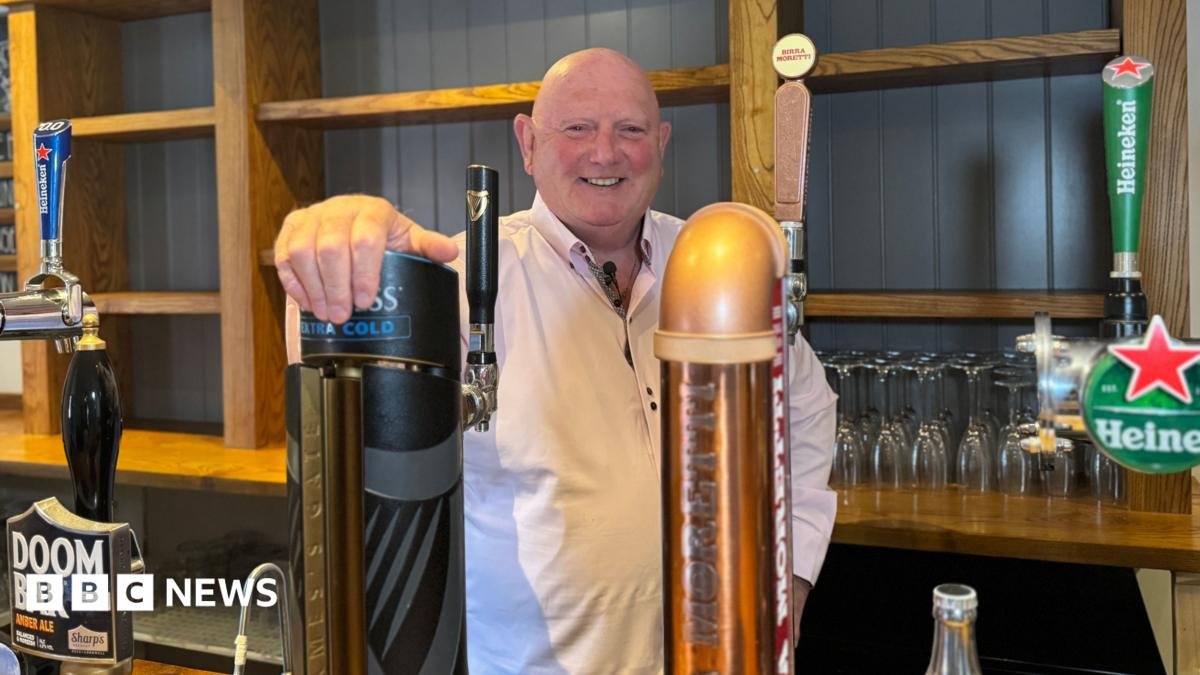
Randy Barnette, founder of the Virginia-based Ornery Beer Company, is almost two years past due on a $500,000 EIDL he took out in February 2021. Before Covid hit, he was actively searching for a space to open a second location of the Ornery Beer Company Public House, his restaurant and bar that features Ornery brand beers. The EIDL funds presented an opportunity to stabilize the business but also facilitate expansion; at the time, no bank or individual investor could have provided a six-figure loan at such a low interest rate, so he wasn’t dissuaded by the need to sign a personal guarantee. “I literally got an email from the SBA on a Monday, and a couple of signatures on DocuSign later, there was a half million dollars in our account in 48 hours,” Barnette said. “It was so easy, I was afraid I was falling for a scam.”
But when the expansion plans hit snafus, Barnette soon found himself underwater and struggling to keep up with his loan payments. After several costly real estate deals fell through, he was eventually able to open a second restaurant, which is still operating, but declining sales forced him to downsize the production brewery and shutter the original restaurant.
As the number of EIDL delinquencies rise among independent restaurant owners, some observers blame the SBA for relaxing the standards for creditworthiness too much post-Covid and approving loans to small businesses that were beyond their means to repay.
“When you’re drowning in the ocean and that lifeboat comes by, you don’t count to see if it has enough oars, you just hop in,” said John Benson, a small business attorney in Doylestown, Pennsylvania, whose firm has seen a significant uptick in inquiries from restaurants struggling to manage EIDL debt. “These owners could not possibly have imagined inflation the way it is, tariffs coming into play or immigration affecting their labor force. The vast majority of them did the very best they could. They put the money into things that they thought would help the business.”
Despite the government’s aggressive collection tactics, which include recent SBA efforts to prosecute Covid-related EIDL and paycheck protection program fraud through Operation No Doze, Benson says his firm has had success working with the treasury department to reinstate loans that entered collection or settle his clients’ debts for lesser amounts.
For restaurants that are saddled with sizable EIDLs, the monthly installments are a significant drag on their business. “For what we’re paying per month, if you break it out over a year, it’s the cost of a high-level manager in our company,” said Dan Jacobs, chef and co-owner of DanDan and EsterEv in Milwaukee. His business pays close to $5,000 a month to service the loan he took out in 2021, which he said cuts his profit margin by one-third. “Meanwhile, we’ve seen close to a 15% drop in business from last year. And there’s no real reason for it, except the fact that the economy is trash.”
To provide extra relief for struggling borrowers, the SBA instituted a hardship accommodation plan in November 2022 that allowed businesses to reduce their monthly payments after the deferment period ended, but the program expired last March. “Once the hardship program ended, we stopped making payments altogether,” said Barnette. “Because we can’t. We’ve been struggling.” His loan was transferred to the treasury department for collection last summer. With compounded interest, penalties and fees, his total bill jumped from $530,000 to more than $750,000. “Maybe the smartest thing to do would’ve been to close down two years ago. Not one nickel that we paid after the grace period went to the principal.”
Bankruptcy law in the state of Virginia, where 56-year-old Barnette currently lives, has limited protections for homeowners. If he files for chapter 7 protection, the EIDL loan may be discharged, but the government can put a lien on his personal property; the state’s homestead exemption protects only $25,000 of home equity per individual from seizure. “My home that I’ve lived in for 20 years is the only thing I have of value,” he said. “I don’t have any life savings. I don’t have retirement funds. I’ve dumped everything into this business to make it keep working through the years. If I lose my house, I’ll just be living in a trailer park until I die.”
As a Florida resident, Mazumdar is protected from losing his home should he elect to declare bankruptcy. As of now, he intends to continue paying his monthly installments on time, even while his business continues to operate in the red.
With the midterm elections fast approaching, Barnette holds out hope that new leadership in Washington could provide relief for struggling borrowers. “Frankly, I’m just kicking the can down the road, trying to improve the health of the business, until Congress changes things,” he said. “We’re all holding our breath in the restaurant industry, hoping the political climate changes and maybe our leaders will do something about this.”