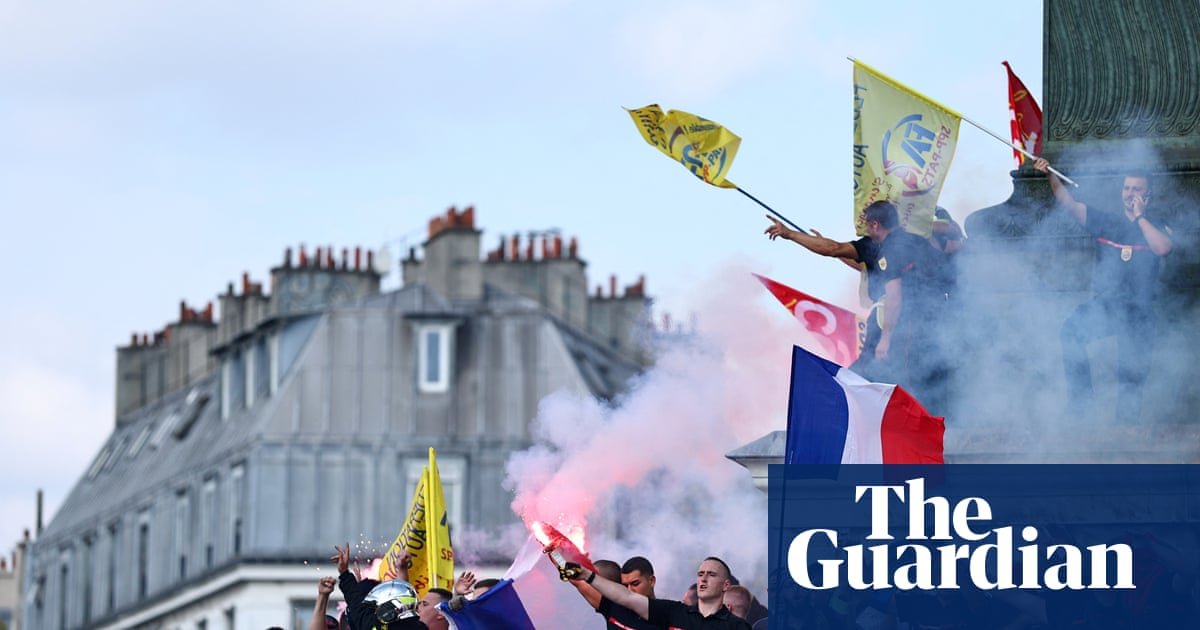
Public-sector workers, including firefighters, take part in a protest at the Place de la Bastille in Paris in September.
/Getty Public-sector workers, including firefighters, take part in a protest at the Place de la Bastille in Paris in September.
/Getty France’s dilemma: protesters demand spending as markets require fiscal restraint Waves of protests expose debt crisis faced by French government, but political wrangling is stalling an escape plan.
Is there a way out?
Eight years have passed since rising fuel prices brought the gilets jaunes (yellow vest) demonstrators to the streets of France, prompting the first big crisis of Emmanuel Macron’s time in the Élysée Palace.
As the French president contemplates his exit next year, turmoil has again gripped the streets in the form of student protests, but this time the financial markets are unhappy too.
As Emmanuel Macron contemplates leaving the Élysée Palace in 2027, turmoil has hit the streets.
/Getty Investors are concerned about the government’s failure to bring spending under control and end a long period of “fiscal incontinence”.
Financial markets are unnerved by similar trends in the UK, the US and more recently Italy, causing jitters in global bond markets.
But it’s France that has become the biggest worry, hemmed in by debts across the public and private sectors, limiting their scope to dig the country out of a deepening hole.
France’s debt-to-GDP stood at 115.6% in 2025, while its budget deficit was 5.1%, compared with 94.3% and 4.3% for the UK respectively.
In Britain, the chancellor, John Healey, is on course to reduce the budget deficit this year and in 2027.
His French counterpart, Roland Lescure, has promised to follow suit after a rise to 5.4% this year, but has yet to say how.
‘I am panicking’ One victim of the uncertainty is business investment.
A survey by Medef, France’s largest employer federation, showed 82% of firms were pessimistic about the impact of the next government’s economic policy.
In a warning to all politicians, 66% said their business would become vulnerable or even go bankrupt if economic policy remained deadlocked for the next five years. .A rescue operation could be mounted by the European Central Bank (ECB), but France would demand unconditional support when the ECB’s rules say bailouts must come with strict conditions.
Antonio Fatas, a professor of economics at Insead, the European business school, says the political and economic situation has pushed France to the edge of a financial collapse.
“I am very worried about the economic situation because growth is low and it is difficult to see how the dynamics change.
Then you have the debt numbers, which are bad, and the financial markets are thinking the government is not in control.
“If I look at the political situation, I am panicking.
That’s because too many political parties are saying let France burn.
They want a crisis, believing it will improve their share of the vote.” There is much about the economic situation in France that mirrors what has happened in the UK and the US.
A huge spending splurge during the Covid pandemic was followed by another round of subsidies to offset the worst side-effects from Russia’s full-scale invasion of Ukraine in 2022.
Investors have become wary of lending to all three countries, but the rise in interest rates is strongest in France.
Students attach posters to the École des mines, a grand école, in Paris.
Yields go up when bond prices go down.
Japanese investors, typically strong supporters of France as a haven for their savings, have been instrumental in the panic after they found better returns on home turf, heaping further pain on the French treasury.
Political turmoil According to many metrics, it is difficult to see why France should be so badly affected.
The French economy has many things going for it, from relatively low electricity prices to better than average infrastructure.
The schools that are the focus of recent protests are better funded than the OECD average.
A protester throws a teargas canister fired by police at a demonstration of high-school students in Bordeaux.
/Getty On the debit side of the ledger, Macron’s plan to raise the pension age from 62 to 64, saving tens of billions of euros from an almost entirely socialised retirement system, stalled at 62 and nine months after parliament was deadlocked after the 2024 snap election.
This might have mattered less if the economy was growing, but Macron’s much-vaunted economic revival remains stuck in first gear.
Laurent Warlouzet, a professor of history at the Sorbonne, says it is understandable that international investors are confused about France when Marine Le Pen, the frontrunner in presidential elections next year, says she will roll back the retirement age to 62 and at the same time introduce a “debt brake” via a referendum, restricting further borrowing. .He said: “The far right used to be a spendthrift populist force, especially under Le Pen’s leadership, broadening the appeal of National Rally voters in the country’s rust belts.
In 2016–17, she still wanted France to leave the eurozone, which she regarded as a straitjacket.” skip past newsletter promotion after newsletter promotion Warlouzet, the author of Liberty, Solidarity and Community: capitalism and European integration, 1945 to the present, added: “Nowadays, Le Pen has become an improbable fiscal hawk.
How can she reconcile this with her voters’ demands for more nurses, teachers, police officers and judges?” Marine Le Pen attends a session at the National Assembly on 8 October.
/Getty ‘Too big to save’ Erik Britton, the director of Fathom Consulting, an international advisory firm, says the prospect of a runoff between Jean-Luc Mélenchon, the leader of the leftwing La France Insoumise (LFI), and Le Pen next April has spooked investors more than the failure to bring down the annual deficit.
“What has changed is the likely runoff.
In the second round, it now looks likely that Le Pen will contest the presidential election against Mélenchon from the far left.
Le Pen’s election might mean a 20% risk of Frexit: Mélenchon’s election, though less likely on current polling, would have a much higher risk of Frexit.” Britton says the collapse of the centre ground would have implications far beyond its borders.
“Where France goes, the euro area as a whole tends to follow.
If it led to another test of the euro, all the considerations about debt and debt mutualisation would resurface, and bond yields would pop right across the euro area (perhaps with the exception of Germany) and beyond.” It may seem improbable for financial market traders to consider France’s exit from the euro when it has occupied a central position in the single currency since its inception.
Yet it is understood several eurozone finance ministers and ECB officials have made representations to the French government, urging it to devise a budget formula that will gain a majority in parliament and a win over leading lenders.
Without a budget, France may be left to fend for itself.
And if that means traders boycott French bonds without a huge interest rate premium, the country may be forced to default on its debts.
A bailout would also be expensive. .As the US Nobel prize-winning economist Paul Krugman said recently: “If France does need to be bailed out, it would be extremely expensive.
As the second largest economy in the eurozone, France may have crossed the line from too big to fail to too big to save” Dhaval Joshi, an independent City economist, said: “Ultimately therefore, France will have to make painful adjustments to bring its debt maths back under control.
Just like Italy, Spain (and, of course, Greece) did a decade ago, from which these southern European economies have emerged much stronger.
Experts suggest Le Pen’s election could mean a 20% risk of Frexit.
Photograph: Jeff J Mitchell/Getty “The crucial question is how much political pain France must go through before it makes, or is forced to make, this adjustment.” The head of France’s central bank, Emmanuel Moulin, denied last week that France needed help from the ECB, but inflamed the situation by adding the rider, “not at this point”.
Albert Edwards, a senior global strategist at Société Générale, said France may survive the onslaught from bonds market traders – some of them termed vigilantes for their habit of sniffing out weak nations – should another country begin to look vulnerable.
“Although France has been in the crosshairs recently, the bond vigilantes’ focus is merely rolling from one market to another.
Next month their attention might be back on Japan, the UK or indeed the US.
“It is the way of the bond vigilantes to jab away and test each market to find out which is the weakest before launching an all-out attack,” he said.
Explore more on these topicsFrance Economics Protest Investing Bonds Europe Emmanuel Macron features Share Reuse this content